Refinancing
Rate and term refinance
The cleanest refinance there is. Same balance, new terms. We run the break-even math before you fill out an application and tell you honestly if it is not worth doing yet.
How the rate and term refinance works
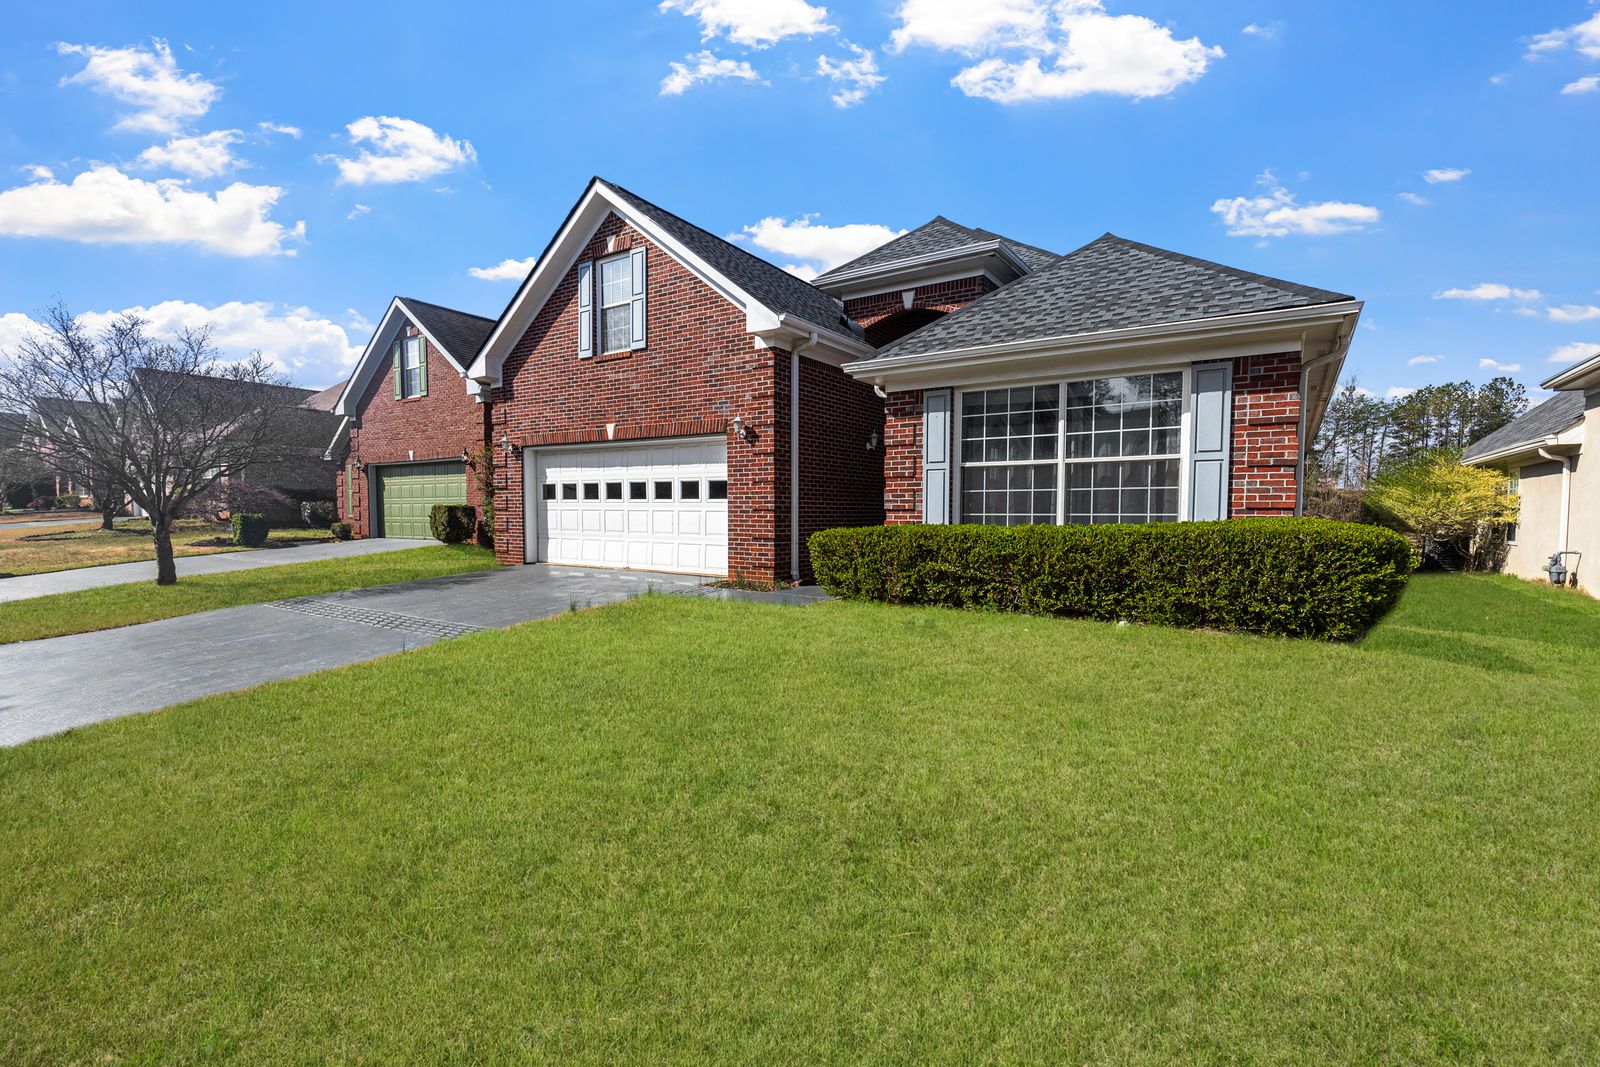
A rate and term refinance pays off your existing mortgage with a new one. The balance stays roughly the same, and what changes is the interest rate, the number of years remaining, or both.
The only number that matters is the break-even point: total closing costs divided by monthly savings. If it costs $4,800 to refinance and you save $210 a month, you break even in 23 months. If you plan to be in the house four more years, that is a clear yes.
Shortening the term is the underrated version. Moving from 27 years remaining on a 30-year to a fresh 15-year raises the payment but can cut six figures of lifetime interest on a typical metro Atlanta balance.
What you get with us
Not program features. The things our office does on every file of this type.
Break-even analysis first
Before an application, before a credit pull. If the math does not work we will tell you to wait.
Appraisal waiver screening
Many refinances qualify for a property inspection waiver, which removes a $600 cost and a week of calendar.
Skip-a-payment explained honestly
Yes, you skip a month. No, it is not free, and we show you exactly where it lands in the payoff.
Escrow refund tracking
Your old escrow account is refunded. We tell you when to expect the check so you do not double-count it.
Term-shortening comparison
Every quote includes a 15-year and 20-year version alongside the 30.
PMI removal review
If your home appreciated past 20% equity, we check whether a refinance or a simple appraisal request is cheaper.
Step by step
Six stages, and what each one actually asks of you.
Numbers conversation
Send us your current statement. We calculate break-even and give you a yes, a no, or a wait.
Application
Ten minutes online. Income and asset documents upload from your phone.
Lock
We lock the rate when you approve the quote, not before.
Valuation
Either an appraisal waiver or a standard appraisal, and we know within 48 hours which one you got.
Underwriting
Refinance files are usually lighter than purchases. Two weeks is typical.
Closing and rescission
Sign at home or at the office, then a three-day federal rescission period before the loan funds.
Why people choose it
Lower rate
The obvious one, and still the most common reason our clients call.
Shorter term
Cut years off the payoff without refinancing into a longer clock.
Drop mortgage insurance
Equity growth can remove the monthly insurance charge entirely.
Leave an adjustable rate
Move off an ARM before the adjustment period starts.
What moves your pricing
Six levers underwriting actually looks at. Two of them you can change before you apply.
| Factor | How it affects you |
|---|---|
| Current rate gap | The spread between your rate and today's market. |
| Time in home | How long you plan to stay decides whether break-even matters. |
| Closing costs | Title, appraisal, origination and prepaid escrow. |
| Equity position | More equity means better pricing and no insurance. |
| Credit score | Same pricing bands as a purchase loan. |
| Remaining term | Restarting a 30-year clock can cost more even at a lower rate. |
Programs people compare this with
- Cash-out refinanceReplace your mortgage with a larger one and take the difference in cash at closing.Compare
- Home equity line of creditA revolving line against your equity that leaves your first mortgage exactly where it is.Compare
- Conventional loanThe workhorse loan for buyers with steady income and reasonable credit. Down payments start at 3%.Compare
Questions about this program
Sometimes. On a $450,000 balance half a point is real money and break-even can land under two years. On a $180,000 balance the same half point may take five years to pay back. Send us the statement and we will run it.
Not always. A large share of refinance files qualify for an appraisal waiver, which saves roughly $600 and about a week.
Two to three weeks is typical for us, plus the mandatory three business day rescission period after signing.
Yes. There is no waiting period on most conventional rate and term refinances, though some programs have a six-month seasoning requirement.
Magnolia Lending Group
Ready to look at a rate and term refinance?
A pre-approval takes about four minutes to start and one business day to issue. No cost and no obligation.
Free consultation. Sample rates and assistance amounts shown on this site are illustrations, not offers.